Home Affordability Calculator
Find out how much house you can afford. Enter your income, monthly debts, down payment and mortgage rate to see your maximum home price and estimated monthly payment.
Maximum Home Price
$330,370
with $50,000 down → $280,370 loan
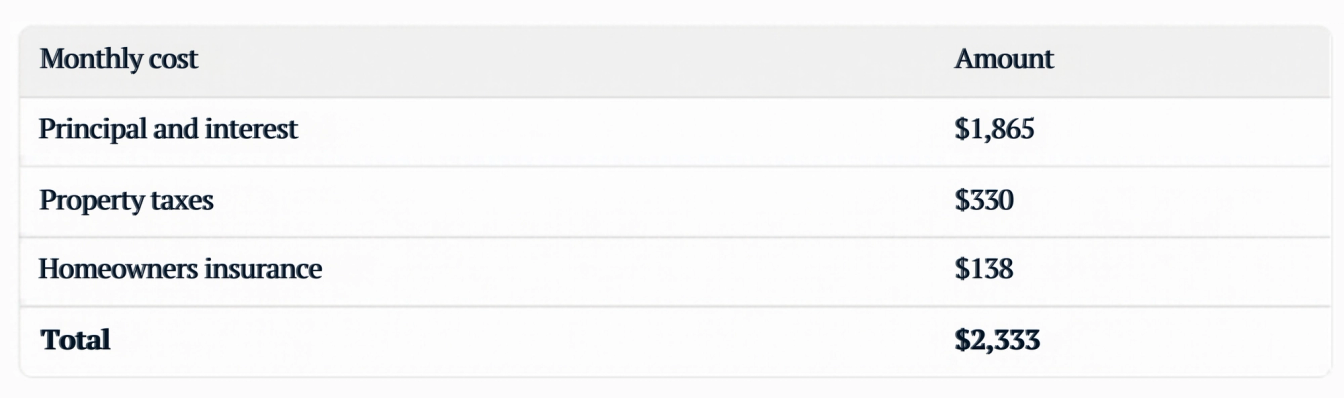
Monthly Payment Breakdown
What is a home affordability calculator?
A home affordability calculator estimates the most expensive home you could buy based on your income, your debts and your down payment. It turns those numbers into a monthly payment limit, then works out what price fits inside it. Use it before you start house hunting to set a realistic search range. It shows a ceiling, not a recommendation. You may feel better buying for less.
How to use this calculator
- Enter your annual household income before taxes.
- Enter your monthly debt payments, such as car loans, student loans and credit card minimums.
- Enter your down payment.
- Enter the mortgage rate (APR) you expect, and pick a loan term: 15, 20 or 30 years.
- Enter the property tax rate for the area where you want to buy.
- Press Calculate Affordability to see your maximum home price, loan amount and monthly payment breakdown.
The fields start with example values. Replace them with your own.
How the calculator works
Many lenders look at two limits, known as the 28/36 rule:
- Housing limit: your monthly housing cost should be no more than 28% of your gross (before-tax) monthly income.
- Total debt limit: your housing cost plus all other monthly debts should be no more than 36% of your gross monthly income.
The calculator uses whichever limit is lower to set your maximum monthly housing payment. Housing cost here means loan principal and interest, property taxes and homeowners insurance. It then finds the home price where that payment fits. Homeowners insurance is estimated at about 0.5% of the home price per year.
Example: the calculator’s starting values
Income $100,000, monthly debts $400, down payment $50,000, 7% rate, 30-year loan, 1.2% property tax.
- Gross monthly income: $100,000 ÷ 12 = $8,333
- 28% housing limit: $2,333
- 36% total debt limit, minus $400 of debts: $2,600
- The lower limit wins, so your housing budget is $2,333 a month
- Maximum home price: about $330,370, with a loan of about $280,370
How your choices change the result
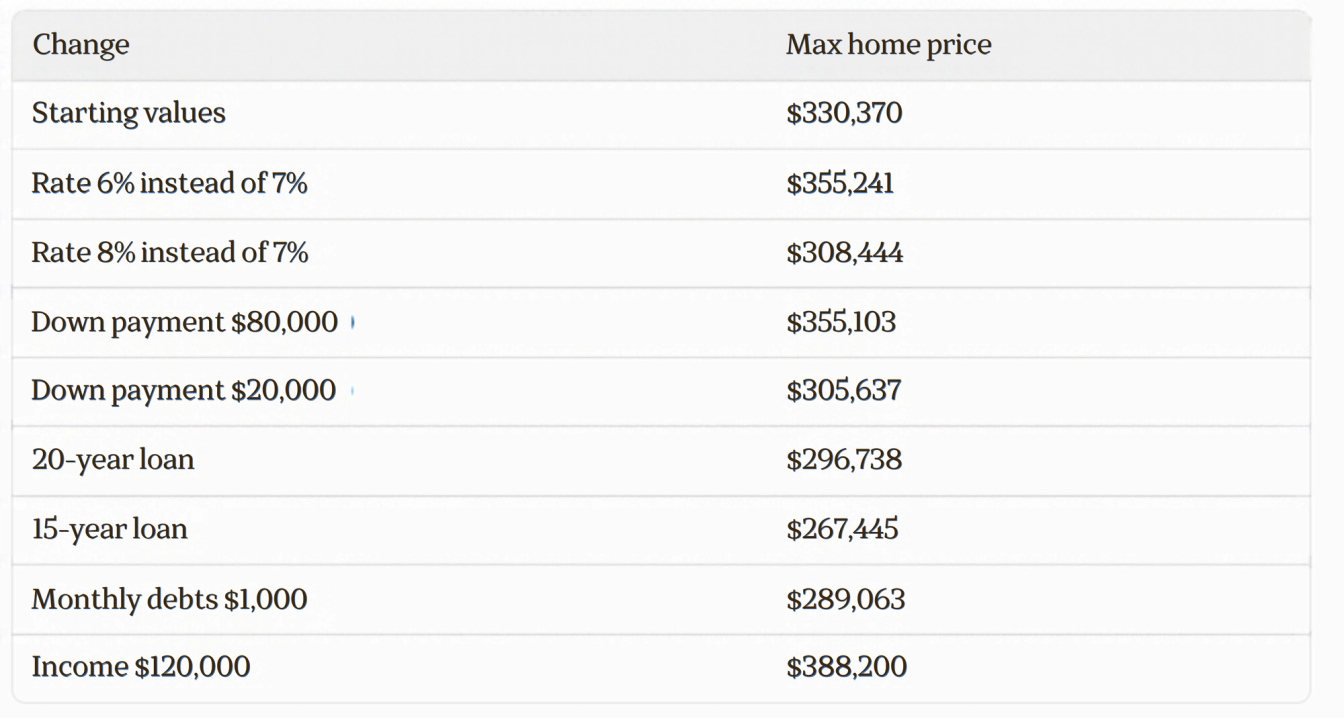
Same example, one change at a time:
A few things stand out:
- Rates matter. One point lower adds about $25,000 to the price you can afford.
- Debts can become the limit. With $400 of debts the 28% limit applies. At $1,000 of debts the 36% limit takes over, and the price drops.
- Extra down payment helps. Each extra $10,000 down adds about $8,200 to the price.
- Shorter loans cost more per month, so the same budget buys a cheaper home. You also pay less interest overall.
What the calculator does not include
- Private mortgage insurance, which often applies when you put down less than 20% on a conventional loan
- HOA fees
- Maintenance and repairs
- Utilities
- Closing costs
- Your credit score (it affects the rate you are offered, so enter the rate you expect) Add these to your budget before you decide.
Tips before you buy
- Do not treat the result as the amount you should borrow. Check it against your real monthly budget.
- Leave room for savings, emergencies and other goals.
- Compare rates from more than one lender.
- Ask a lender for a pre-approval to see what they would actually offer.
Frequently Asked Questions
With the calculator’s starting values ($400 monthly debts, $50,000 down, 7% rate, 30-year loan), the answer is about $330,370. Your number will change with your debts, down payment, rate and taxes.
It is a guideline many lenders use. Your housing costs should be no more than 28% of your gross monthly income, and your total monthly debts no more than 36%. Lenders may approve loans outside these limits, and staying inside them lowers your risk.
Yes, mostly through the interest rate. A lower score can mean a higher rate and a smaller price. The calculator does not read your score, so enter the rate you expect to get.
Yes. The calculator uses the tax rate you enter and adds it to your monthly cost. Tax rates differ by area, so check your county.
A bigger down payment means a smaller loan, so the same monthly budget buys a more expensive home. It can also help you avoid private mortgage insurance.
Not necessarily. The result is a ceiling based on income ratios, not advice. Many buyers choose to spend less to keep room in their budget.
Your total debt limit is 36% of income. Higher debts leave less room for housing, so the maximum price falls.
Before you rely on this result
The figure is a lending ceiling derived from income ratios, not advice about what you should borrow. It takes no account of childcare, commuting, existing goals or the possibility of your income changing. Many buyers deliberately borrow well below the maximum.
Related Finance calculators
See all Finance →- Salary CalculatorConvert salary between hourly, daily, weekly, monthly, and annual pay.
- Discount CalculatorFind sale price, discount percentage, or original price.
- Compound Interest CalculatorSee how your investments grow with compound interest over time.
- Income Tax CalculatorEstimate 2026 US federal income tax with a bracket-by-bracket breakdown.
- CAGR CalculatorCompound Annual Growth Rate — find CAGR, future value, present value, or time to goal.
- Auto Loan CalculatorCar loan calculator with trade-in, down payment, and tax.
More from Finance
View all posts →Longer reads from our finance collection.